Price before going on the slopes
Bought with the lift ticket, using the history of previous days and seasons.
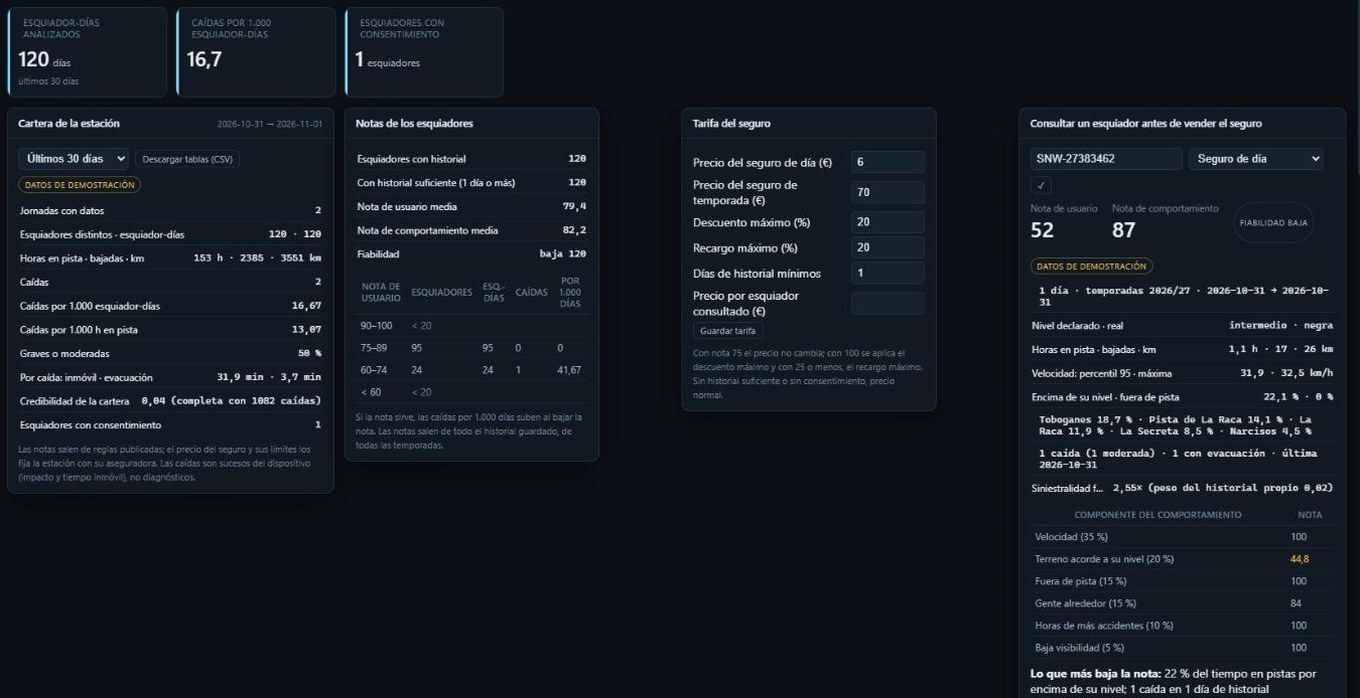
Bought with the lift ticket, using the history of previous days and seasons.
A behaviour score and a skier score, from 0 to 100, with the reasons in plain words.
Normal day and season price, maximum discount and surcharge, and minimum days of history.
Insurers query and buy scores and KPIs via API, and every query is recorded.
Exposure, frequency, severity, relativity and credibility per risk factor.
Without it, normal price and anonymous data only. No positions and a pseudonym per insurer.
While the skier has their normal insurance, every day is measured: how much they ski, how, and what happens to them.
A behaviour score and a skier score, from 0 to 100, with their reliability and the reasons in plain words.
Before going on the slopes, the resort raises or lowers the insurance with the score, within its limits, if the skier agrees.
With its key, it queries the score and KPIs of anyone who gives it consent. Every query is recorded for invoicing.
The data an actuary uses to build a rate, measured by the device rather than declared by the customer.
| What it includes | What it is for | |
|---|---|---|
| History | Days and seasons, declared and real level, usual areas, hours, runs and km | Knowing who they are and how much they are exposed |
| Behaviour | Speed, terrain against their level, off-piste, people around, time of day and visibility | The risk factors highlighted by ski accident studies |
| Previous accidents | Falls by severity, time immobile, evacuations and last fall | Frequency and severity: what makes a claim expensive |
| Scores | Skier score, behaviour score, reliability and reasons | A score ready for rating and explainable to the person |
| Portfolio | Tables per factor with frequency, relativity and credibility, and falls per score band | Building and validating the rate without personal data |
| Daily conditions | Hours of lifts stopped by cause, low visibility and snowfall | Parametric insurance: automatic payout for closures or bad weather |
No. It is bought with the lift ticket, as always. The price comes from the history of previous days and seasons, when the person skied with normal insurance.
The normal price. The adjustment starts once they reach the minimum days of history set by the resort.
It uses the same score with its own normal price: the resort sets one for day insurance and another for season insurance.
The resort with its insurer: normal price, maximum discount and maximum surcharge. The platform calculates the scores with published, explainable rules.
The anonymous portfolio tables and, for anyone who gives it consent, their history, scores and reasons, with its own pseudonym and no positions.
The dashboard shows falls per 1,000 ski days in every score band. With full seasons and the insurer's paid claims, weights and thresholds are tuned.
We will show you the platform with your resort's map. No commitment.